Last updated: November 20, 2026
Key Takeaways
- A bucketed setup should let you see emergency money and other goals at a glance.
- A bucketed savings account works when labels reduce stress during surprises, not when they hide cash.
- Pick the account that keeps emergency savings obvious, quick to reach, and separate from spending.
- The bank app matters more because you will use it more often than the rate.
Quick Answer
Choose a savings account with subaccount buckets for emergency savings if it gives you clear labels, fast transfers, and easy balance checks. In practice, the best fit is the account that lets you separate emergency money from other goals without making the app harder to use.
A savings account with subaccount buckets works best when the app lets you name goals, move money fast, and keep your emergency fund easy to scan. Choose the account that makes your emergency money simple to see, simple to move, and hard to confuse with spending cash. The steps below will help you sort the features that matter from the ones that just look nice.
This is information, not financial advice. For your own situation, a qualified adviser should review any money decision.
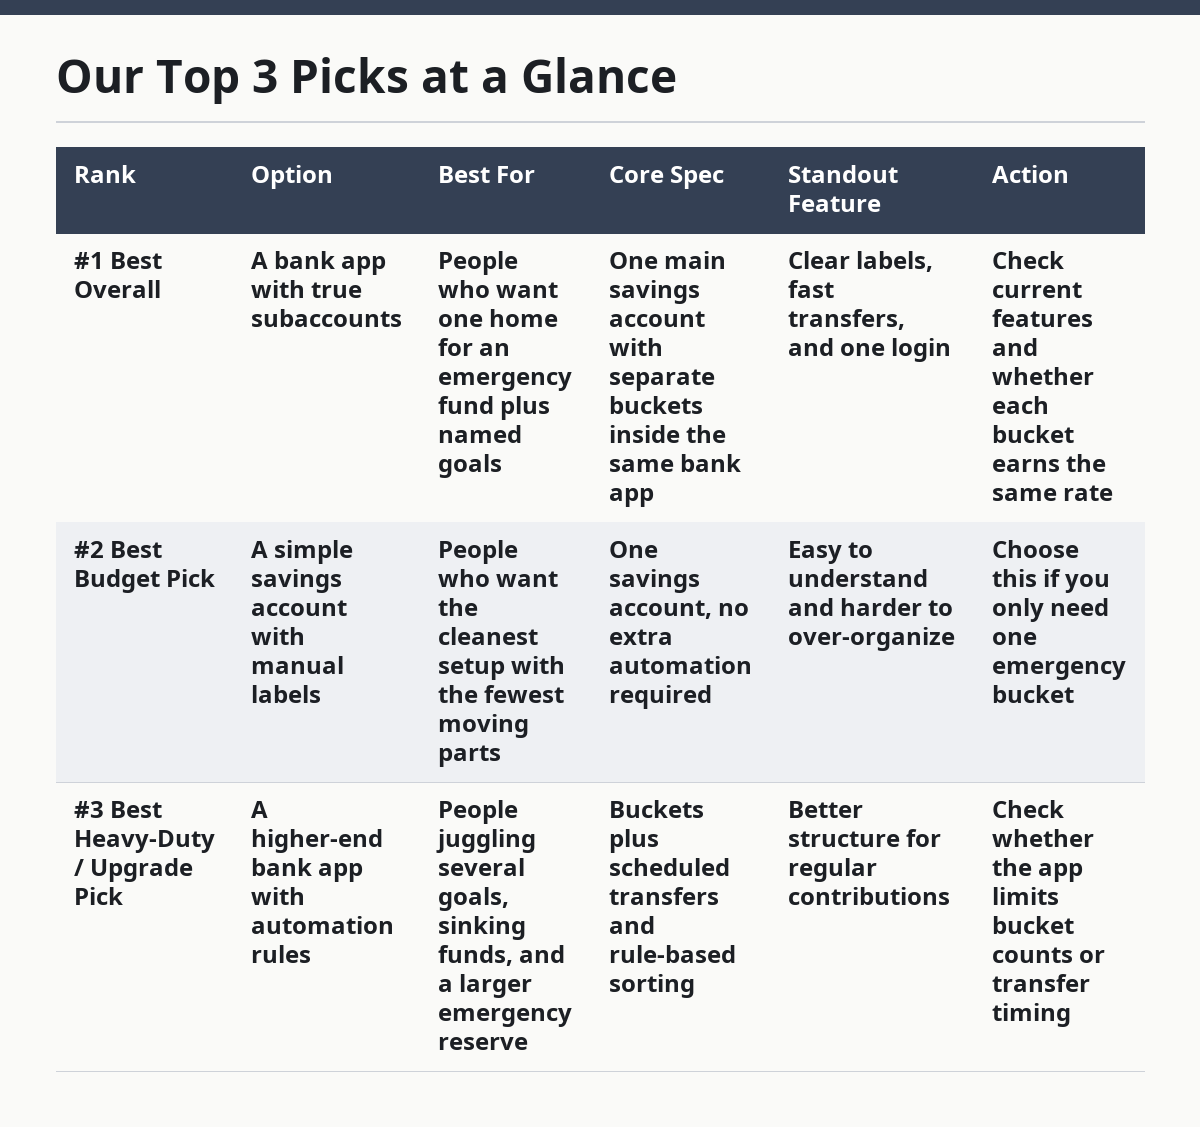
Our Top 3 Picks at a Glance
| Rank | Option | Best For | Core Spec | Standout Feature | Action |
|---|---|---|---|---|---|
| #1 Best Overall | A bank app with true subaccounts | People who want one home for an emergency fund plus named goals | One main savings account with separate buckets inside the same bank app | Clear labels, fast transfers, and one login | Check current features and whether each bucket earns the same rate |
| #2 Best Budget Pick | A simple savings account with manual labels | People who want the cleanest setup with the fewest moving parts | One savings account, no extra automation required | Easy to understand and harder to over-organize | Choose this if you only need one emergency bucket |
| #3 Best Heavy-Duty / Upgrade Pick | A higher-end bank app with automation rules | People juggling several goals, sinking funds, and a larger emergency reserve | Buckets plus scheduled transfers and rule-based sorting | Better structure for regular contributions | Check whether the app limits bucket counts or transfer timing |
How I rank the options
The best fit is the one that keeps your emergency fund visible without turning it into a puzzle. A bucketed savings setup should help you answer one question in seconds: “How much is set aside for the emergency fund, and how much is spoken for?”
That matters because some apps make bucket names obvious and others hide them behind extra taps. A name like Emergency Fund, Car Repair, or Medical beats a vague “Savings 2” every time.
Here are the main features to compare:
- bucket labels you can rename
- whether buckets sit inside one savings account or across separate accounts
- transfer speed between checking and savings
- whether the app shows each bucket balance clearly
- whether the bank limits bucket counts or transfer rules
- whether the emergency fund can be kept apart from vacation or tax money
- whether the setup stays simple enough to use during a real crisis
What makes a bucketed savings account worth using?
A bucketed savings account is worth it when the labels help you stay calm during a surprise bill, not when they give you more places to forget money. The whole point is separation inside one institution, with goal labels that tell the money what it’s for.
Picture this: you open the bank app at 9 p.m. after a roof leak, and you need to know where the emergency cash lives. If the app shows one emergency bucket and maybe one backup bucket, you can act fast. If it shows eight unlabeled pockets, the system is doing more harm than good.
The best setup usually has three traits:
- One visible emergency bucket for true crises
- A few named subaccounts for other goals you do not want mixed in
- A simple transfer path so moving cash does not become a chore
The catch is that “bucket” can mean different things at different banks. Some institutions call them subaccounts, some call them goals, and some call them spaces or jars. The name matters less than the behavior: can you separate the money, label it clearly, and access it without confusion?
When the feature works, it helps you avoid raiding your emergency fund for non-emergencies. When it fails, it becomes decoration.
How to choose a savings account with subaccount buckets
Pick the account that makes your emergency fund obvious, fast to reach, and hard to mix up with other goals. That means checking the app first, not the headline rate. Rates vary by country and change often, so the rate alone should not drive this choice.
Picture this: you already have cash set aside, but it keeps getting blurred with holiday savings, a new laptop fund, and rent money. You need a structure that keeps the emergency fund from becoming a junk drawer. The right account should solve that in the app itself.
Follow these steps in order:
- Open the app and inspect how the buckets appear on the home screen.
- Label each bucket with plain names like Emergency Fund, Car Repair, or Medical.
- Check transfers between checking and savings for speed and any limits.
- Review the bucket count to see whether the bank caps how many you can create.
- Compare visibility by looking for balances shown per bucket, not buried in menus.
- Confirm separation so emergency money does not sit next to money you plan to spend soon.
- Read the terms for rules on withdrawals, transfers, and possible fees.
A good bucket system should help you decide in seconds, not invite more tinkering. If the bank app makes you manage a spreadsheet just to know where your emergency fund sits, the feature is too clumsy for the job.
A quick decision rule
Choose the account if the emergency bucket is visible in one tap and you can rename it without friction. Skip it if the app buries bucket balances, forces awkward labels, or makes transfers feel slow.
Why the bank app matters more than the headline rate
The bank app matters more because you will use the interface far more often than you will admire the rate. A slightly better rate does not help if you never remember where the money is or how to move it.
Picture this: a tire blows out, the vet bill lands, or the fridge dies on a Friday night. In that moment, the cleanest app wins. You want a bank app that makes the emergency fund easy to find and easy to move, not one that looks polished but hides the balances behind three screens.
Look for these app traits:
- bucket balances shown clearly on the dashboard
- labels you can change without calling support
- instant or same-day transfers where available
- plain language in the menu, not banking jargon
- simple alerts when a transfer lands or a balance changes
Here’s the catch: some apps make buckets look neat but do not give you much real separation. Others show excellent structure but make it hard to move money at the exact moment you need it. The best app sits between those extremes.
A weak app can turn a smart system into dead weight. If you need a cheat sheet to find your own savings, the account is not helping enough.
What to watch for in the terms
Read the rules for transfer timing, withdrawal limits, and fees. Those terms change by institution and country, and they decide whether your emergency money is useful on a random Tuesday or only on a bank’s schedule. The Consumer Financial Protection Bureau and the FDIC both publish consumer guidance on account terms and deposit insurance in the United States.
Which bucket setup works for an emergency fund?
A simple, named emergency bucket usually works best for most people, because it keeps the money distinct without creating false layers. If you need extra buckets, keep them tied to real risks, not wishful thinking.
Picture this: you have one bucket for emergency cash, one for car repairs, and one for medical costs. That can be a clean setup if each label maps to a real bill you might face. It becomes a mess when the labels are just storage labels with no purpose.
The strongest use cases are clear:
- One emergency bucket for job loss, medical bills, or urgent repairs
- One backup bucket if you want a small cushion separate from the main fund
- A few goal labels for costs you know are coming, like annual insurance or a deductible
The weak use cases are just as clear. Don’t use buckets to hide spending money from yourself. Don’t build five savings pockets if you only need one emergency fund. And don’t split the money so finely that you can’t tell whether you are actually funded.
A bucket system should reduce decisions. If it creates more decisions, it has failed. That’s the real test.
Who this is not for
This setup is not for someone who needs one plain account and zero choices. If you freeze when faced with too many labels, a single emergency bucket is better than a busy dashboard.
The honest side-by-side
A bucketed savings account wins for people who want one institution and clear labels; a plain savings account wins for people who want the fewest parts. The better choice depends on how much structure you will actually maintain.
| Criteria | Option A: True subaccounts/buckets | Option B: Plain savings account | Winner for [condition] |
|---|---|---|---|
| Visibility | Balances can be split by goal in the app | One balance, one pot | Buckets for organized savers |
| Setup effort | More initial labeling and rules | Very little setup | Plain account for simplicity |
| Emergency fund clarity | High when labels are used well | High only if you keep one purpose | Buckets for mixed goals |
| Risk of confusion | Higher if many buckets exist | Lower because there is only one pool | Plain account for low-maintenance users |
| Transfer convenience | Often better inside the same app | Depends on the bank’s transfer tools | Buckets if same-app movement matters |
| Goal tracking | Easy to assign names to money | Needs outside notes or a spreadsheet | Buckets for visual trackers |
| Over-organization risk | Real, especially with many buckets | Low | Plain account for easily distracted users |
| Use during an emergency | Good if the app is simple | Good if the money is easy to move | Tie, depending on app design |
| Long-term maintenance | Needs occasional review | Needs almost none | Plain account for set-and-forget users |
The table says the main truth plainly: structure is useful only if you will keep using it. A bucket system solves organization, not discipline.
The specific situations where each option wins
A bucketed savings account wins when you have more than one money goal and you want them in one place. A plain savings account wins when your emergency fund is the only reason the account exists.
Picture this: you save for emergencies, a home repair, and a new furnace in the same year. Buckets help you avoid calling all of that “savings” and then spending the wrong money. But if your only job is holding six months of emergency cash, extra buckets can be a distraction.
Option A: subaccounts or buckets
This setup is strongest if you like visual separation, use named goals, or share your own brain with a bank app that must stay obvious. It can also help if you transfer money on a schedule and want each destination labeled.
The downside is maintenance. Too many buckets can create fake precision, and some banks make the structure feel better than it behaves. If the app buries balances or limits bucket features, the value drops fast.
Option B: one plain savings account
This setup is strongest if you want the emergency fund isolated from everything else with no extra logic. It is easy to understand, easy to monitor, and hard to overcomplicate.
The downside is that you lose visual separation. If you also save for taxes, travel, or home repairs, everything sits in one pool unless you track it elsewhere. That can work, but it asks more of you.
One source worth checking
The Consumer Financial Protection Bureau explains how to compare savings accounts and read account terms; that is a good starting point when you are checking rules and fees. See the CFPB’s consumer resources on savings accounts and deposit accounts, and the FDIC’s deposit insurance resources if you are in the United States. Also review your bank’s own fee schedule and account disclosure before you open anything.
When to reconsider this choice entirely
A bucketed savings account is the wrong tool if the account structure matters more than the emergency money itself. If you are forcing buckets to do the work of a budget, step back.
Picture this: you are juggling rent, credit card debt, and a tiny emergency cushion. In that case, more buckets can create a sense of order without actually improving your cash position. One account and one emergency label may be all you need.
Reconsider the setup if any of these are true:
- You keep forgetting which bucket holds what.
- The app does not show balances clearly on the first screen.
- The bank makes transfers awkward or delayed.
- You only need one emergency reserve and nothing else.
You do not need a fancy structure to be prepared. You need a system you will actually use when something breaks.
The verdict: which one to choose and why
Choose subaccounts or buckets if you keep multiple savings goals and want your emergency fund labeled inside one bank app. Choose one plain savings account if you only want a single emergency reserve and dislike extra moving parts. Neither if the app hides balances, slows transfers, or pushes you into an overcomplicated setup.
That is the clean rule. A bucketed account is for clarity; a plain account is for simplicity. Pick the one that makes your emergency money easier to recognize on a bad day.
How to name emergency fund buckets
Name them by purpose, not by vague labels. “Emergency Fund” is better than “Bucket 1,” and “Car Repair” is better than “Savings Extra.”
Picture this: you open the app after a surprise expense and need to know where the money is in two seconds. A clear name does that job. A cute label does not.
Good bucket names usually do one of three things:
- state the purpose plainly
- match a real expense you expect
- stay short enough to scan quickly
If you need more than one emergency-related label, keep the names specific. “Emergency Fund” can hold true crises, while “Medical” or “Auto Repair” can sit beside it only if those costs are real and recurring in your life.
Are subaccounts good for emergency savings?
Yes, if the buckets make the emergency fund easier to spot and harder to mix up with spending money.
A subaccount works well when you want one home for emergency savings and a few other clearly labeled goals. The CFPB’s savings-account guidance and the FDIC’s deposit insurance resources are both useful references when you compare account terms and protection.
Drafted with AI; not yet reviewed by a person.