How to Get Emergency Money Into Your Checking Account the Same Day

Last updated: November 19, 2026
Quick answer: If you need emergency money into your checking account the same day, the fastest option is usually the one you already have set up and that your bank will let you use now: an internal transfer, an eligible instant transfer, a wire transfer, or debit card cash access at an ATM. The exact result depends on the transfer rail, cutoff time, and whether the source account is already linked and verified.
If you need emergency money in your checking account today, the fastest path is usually an internal bank transfer, an instant transfer through a linked account, a debit card cash withdrawal, or a wire transfer. The right choice depends on what you already have set up, what time you start, and whether you need digital money or physical cash. For banking and transfer timing basics, see the Consumer Financial Protection Bureau’s transfer guidance and your bank’s own funds-availability rules. CFPB, Federal Reserve Regulation CC, FDIC
The fastest route depends on where the money already sits
The fastest route is usually the one that already has a verified transfer path attached to your checking account. If the money is in the same bank, a bank transfer can be immediate or close to it. If it is at another institution, a linked external account with instant transfer may work, but many banks still route it as an ACH transfer, which can take 1 to 3 business days. If you need cash at once, a debit card and ATM may be faster than waiting for a posted transfer.
The point is simple: same-day access is less about the size of the emergency fund and more about the rails already in place. A $200 transfer from a savings account at the same bank can be easier to access than a larger balance at an outside bank with no linked account. A wire transfer can move money quickly, but it is usually the most expensive option and often requires a cutoff time during the business day.
Here is the order I would check it in:
- Move money inside the same bank first. Open the banking app or website and look for a transfer between your savings and checking accounts. If both accounts are at the same institution, the money may show up right away or within minutes.
- Try an instant transfer from a linked external account. Some banks let you pull money in from an outside account instantly if the account is already linked and eligible. This is different from a standard ACH transfer, which is usually slower.
- Use your debit card for cash at an ATM. If you already have the card and the account has available funds, an ATM can give you cash on the spot, up to the daily withdrawal limit.
- Use a wire transfer only if the amount and timing justify the fee. Wire transfers are built for speed, but they usually cost more and often must be initiated before the bank’s cutoff.
A generic article often skips the key distinction between “transfer” and “cash.” A transfer can settle electronically while still leaving you unable to pay a landlord, mechanic, or locksmith who wants bills. If you need money to spend in person tonight, the ATM path matters as much as the transfer path.
How to get emergency money into checking the same day
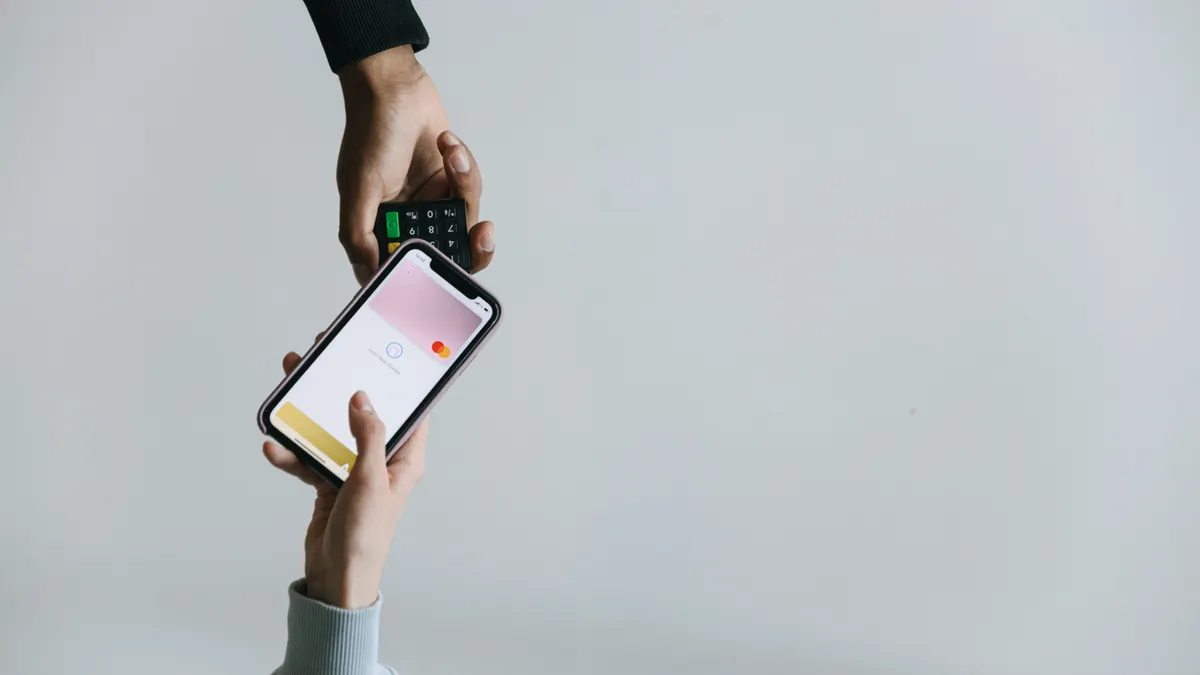
You can usually get emergency money into checking the same day by using the fastest transfer method your bank already supports and starting early enough to beat the cutoff. The procedure is mechanical, not magical: pick the transfer rail, confirm the linked account, choose the amount, and check when the money becomes available to spend.
Use this order when the clock is ticking:
- Open the banking app or website and check for “transfer,” “move money,” or “external transfer.” If the money is already at the same bank, choose the internal transfer option first because it often posts fastest.
- Confirm the source account is linked and verified. If it is an outside bank, the link may need microdeposits or a one-time verification step before any same-day move is possible.
- Choose checking as the destination and enter the amount you actually need. A smaller transfer can be easier to release quickly if your bank has instant-transfer limits or fraud review flags on larger amounts.
- Look for the delivery estimate before you submit. If the screen says “available now,” “instant,” or “same day,” that is the route you want. If it shows the next business day, you are looking at standard ACH timing.
- Submit before the bank’s cutoff time. Many same-day payment and transfer systems depend on business-day processing, so a transfer started late in the evening may wait until the next posting window.
- If the money is still not spendable, use the debit card at an ATM. The transfer may still be pending while your card can access available cash immediately.
- Keep the confirmation number or screenshot. If a transfer stalls, that record helps the bank trace it without starting from zero.
The biggest mistake is assuming that any transfer labeled “electronic” is instant. ACH transfer and wire transfer are both electronic, but they do not behave the same way. ACH is the common low-cost rail for bank transfer activity, and it is often slower. Wire transfer is faster, but it is usually less convenient and may cost more. If you are moving money for a medical bill, tow truck, or rent shortfall, that difference matters.
One more practical point: if you need the money for cash, do not confuse “available balance” with “cash in hand.” Your checking balance may reflect the incoming transfer before an ATM or cashier can use it, but some institutions still place holds or limit immediate withdrawal. That is why a debit card and ATM are part of the emergency plan, not a separate topic.
What will actually post today, and what will not
Only transfers already eligible for same-day processing will post today. That usually means an internal transfer, an instant transfer from a linked account, or a wire transfer started before the cutoff. A standard ACH transfer is the one most likely to miss your deadline.
Here is the practical split:
- Internal bank transfer: Often the fastest when savings and checking are at the same institution. If the bank’s system supports it, the money can be usable almost immediately.
- Instant transfer from a linked external account: Works only if your bank offers it and the source account is already verified. Not every linked account qualifies.
- ACH transfer: Usually the default for moving money between banks. It is reliable, but the timing is usually measured in business days, not minutes.
- Wire transfer: Fast, but more formal. Often used when the amount is large or the deadline is strict.
- Debit card cash access at an ATM: Not a transfer in the banking sense, but it can be the fastest way to turn checking funds into cash.
The common mistake is treating every banking app the same; check your bank’s rules and, if the move matters for a bill or safety issue, consult a bank representative or other financial professional and confirm the timing with a source such as your institution’s transfer disclosures. One institution may let you move money between your own accounts instantly. Another may route nearly everything through ACH unless you request a wire. A third may let you pull money in from outside accounts but cap instant transfers at a specific amount per day. That cap is the reason a $50 transfer may clear instantly while a $2,000 transfer does not.
There is also the problem of “available” versus “posted.” Available means you can often spend or withdraw it. Posted means the bank has fully recorded it. Those are not always the same moment, especially around weekends, holidays, and evening cutoff times. If you initiate a transfer late Friday, “same day” can effectively mean “not until Monday” depending on the rail.
This is where a basic emergency plan saves time. Keep at least one external account linked in your primary bank app before the emergency happens. If you wait until the crisis, you may spend the first 20 minutes just getting verification codes, setting up microdeposits, or discovering that your bank will not allow a first-time instant transfer.
For background on where emergency funds belong and why access speed matters, the hub on where to keep an emergency fund covers the storage side. This page is about the movement side: how the money gets from one place to another when the clock is running. For related setup advice, see the hub on how to build an emergency fund and where to keep an emergency fund.
Can I just use an ATM and my debit card?
Yes, if the money is already in your checking account and your card is active, an ATM is often the quickest way to get physical cash. The catch is the daily withdrawal limit, which can be lower than the amount you need, and the machine may also impose its own limit on a single withdrawal.
That makes ATM planning part of same-day access. If you need $300, a standard card withdrawal may solve the problem in one stop. If you need more than your limit, you may have to make several withdrawals, call the bank to ask for a temporary limit increase, or use another method such as an internal transfer or wire transfer.
A few details matter here:
- Use your own bank’s ATM when possible. It usually reduces the chance of extra fees and can improve cash availability.
- Check the card’s daily limit before you go. The limit is often the hard stop, not the balance.
- Count on business hours only if the ATM is tied to branch cash service. An ATM itself may be open 24/7, but an issue with the card or account is easier to solve when the branch is open.
- Keep the withdrawal amount small and exact when possible. If you need $180, withdrawing $200 may be easier than trying to split it across multiple machines later.
The drawback is obvious: ATM access gives you cash, not a transfer trail to a payee. If the emergency requires a digital payment, such as an online utility portal or peer-to-peer app, cash may not help. In that case, the transfer method matters more than the withdrawal method. If you need to pay a person or business that accepts debit card payment, the card can still save you a second step, but only if your account balance is already available.
When same-day transfer is not enough
Same-day transfer is not enough when the receiving side needs a cleared bank transfer, a larger amount than your instant limit allows, or a payment type your bank will not accelerate. If your transfer is for a cashier’s check, a wire to another bank, a landlord’s portal, or a court deadline, the destination rules can matter more than your source account.
This is the part generic advice misses. Moving money into checking does not guarantee that the next step will succeed. For example:
- A rent portal may accept an online payment but not an ATM withdrawal.
- A mechanic may want cash today, but your bank may cap ATM withdrawals at a level below the repair estimate.
- A wire transfer can be same-day, but only if you send it before the cutoff and the recipient accepts wires.
- An ACH transfer may be free or cheap, but it usually is not the right tool for a same-day emergency.
If the emergency is legal, medical, or safety-related, call the receiving party first and ask what form of payment they will accept right now. That is not a banking trick; it is a timing check. If they want a wire by 3 p.m., a bank transfer that lands tomorrow is the wrong tool.
The trade-off is cost versus certainty. Wires are usually the fastest bank-to-bank route when time matters, but they can be more expensive than ACH. ATM cash is immediate if the funds are already in checking, but the card limit can block you. Internal transfers are often the best low-friction option, but only if the money is already in the same bank.
How to avoid losing an hour to delays
You avoid delays by checking three things before you need the money: linked accounts, transfer cutoffs, and withdrawal limits. Those three details decide whether the same-day transfer works in 5 minutes or turns into a next-business-day wait.
Start with the linked account. If your savings sits at the same bank as your checking, make sure both accounts appear in the app and that transfers between them are enabled. If the savings account is elsewhere, confirm that the external link is already verified. A first-time link often adds extra steps you do not want during an emergency.
Next, learn the cutoff time for the transfer method you plan to use. A bank can support same-day processing and still move slower after a certain hour. That matters on Fridays, before holidays, and after business hours. The difference between 2:30 p.m. and 7:30 p.m. can be the difference between today and tomorrow.
Then check the debit card’s ATM limit. If the limit is $500 and the emergency is $800, you need a second path. If the limit is enough, the card becomes your fastest backup even when the transfer system is sluggish.
A useful habit is to keep one small transfer path already tested and one cash path already available. That does not mean moving your emergency savings around for sport. It means knowing in advance which account can feed checking the same day, which ATM will work with your card, and which method costs extra. The first time to learn that should not be when you are standing in a parking lot after a flat tire.
The practical choice: what I would use first
The best first move is the one that gets usable money into checking with the fewest moving parts, and that is usually an internal bank transfer. If the money is at another bank and already linked, an instant transfer or wire transfer may be faster. If you need cash immediately, the debit card and ATM route is the most direct.
I would not use ACH as the first choice for a true same-day emergency unless I had no other option and the deadline was soft. ACH is fine for ordinary transfers, but it is not the tool I would pick when I need money within hours. I also would not rely on a transfer I have never tested under non-emergency conditions. A verified link, a known cutoff time, and a debit card that works at the ATM are worth more than a vague promise from a banking app.
The rule is simple: same-day access depends on the rail, the cutoff, and whether the money is already linked to checking. If those three things are in place, you can usually get emergency money into your checking account the same day without guessing.
Key Takeaways
- The fastest same-day path is usually an internal transfer, an eligible instant transfer, a wire, or ATM cash access through a debit card.
- ACH is the common slow lane for bank transfers, so it is a poor first choice when time is tight.
- A linked external account, a bank’s cutoff time, and your ATM withdrawal limit decide what you can actually use today.
- “Available balance” and “cash in hand” are not the same thing.
- If the transfer path is not already set up, the emergency may outrun the banking app.
Can I move emergency savings to checking instantly?
Sometimes, yes. If the savings and checking accounts are at the same bank, the transfer can be immediate or close to it.
Drafted with AI; not yet reviewed by a person.